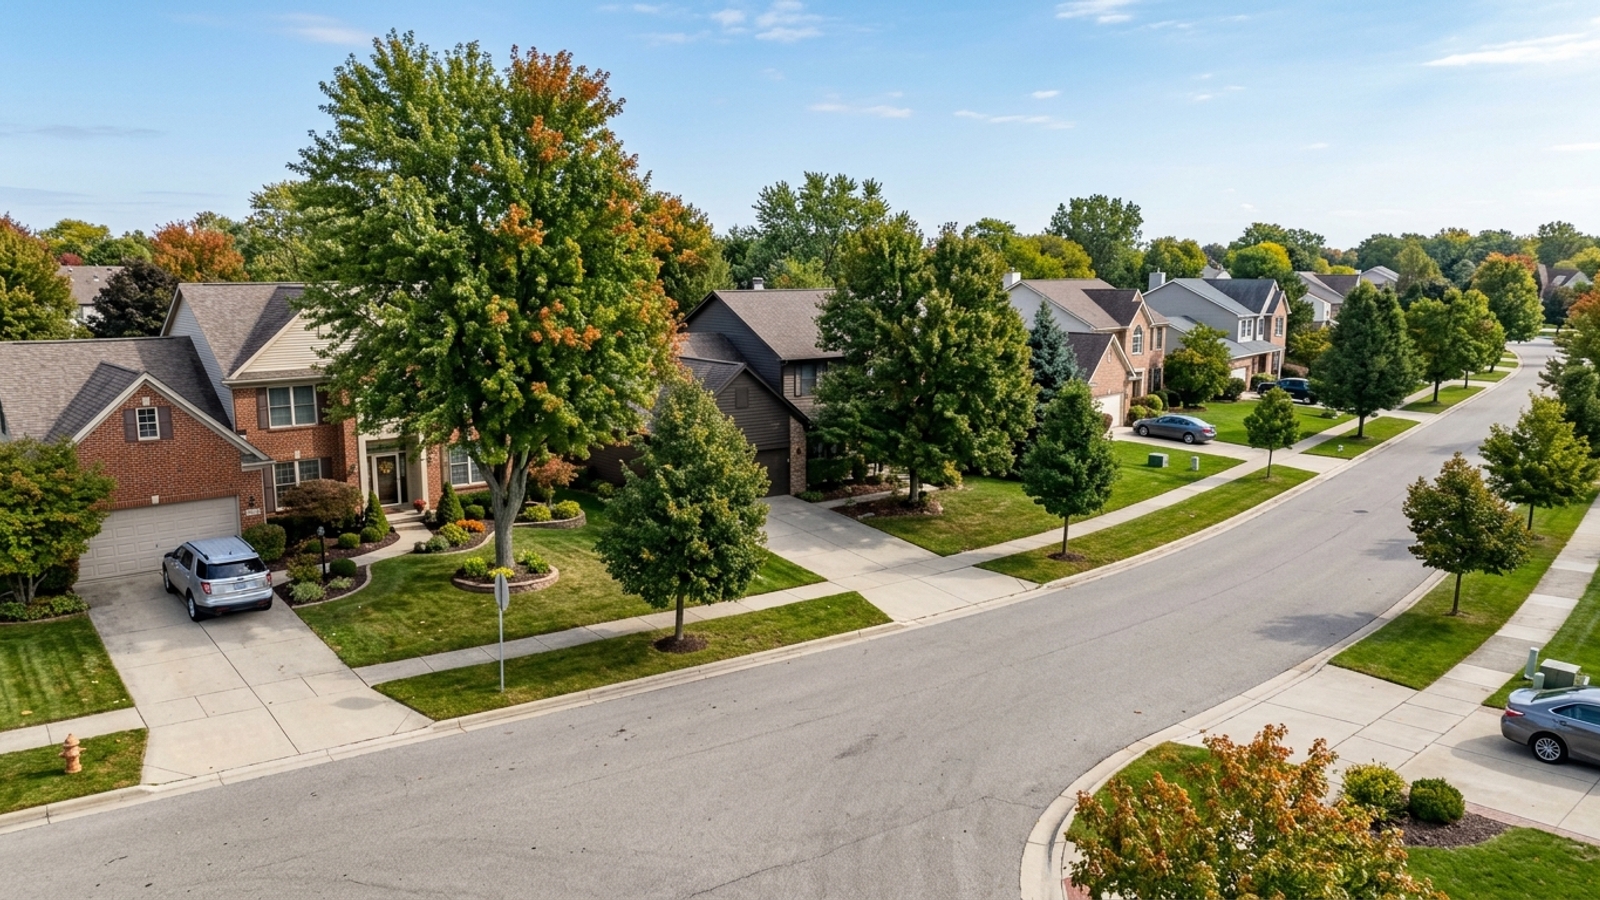
The median sale price in South Lyon, MI recently hit roughly $342,000, with homes spending about 30 days on the market. Buying a home in South Lyon, MI requires careful financial planning. If you’re trying to scrape together enough cash to compete in a market where 35% of local listings sell above asking price, that’s a real pressure point.
The good news is that you don’t have to do it entirely on your own. Oakland County and the state of Michigan both run assistance programs specifically for buyers purchasing in ZIP code 48178 and the surrounding area – programs that can cover a meaningful chunk of what you need to close.
Overview of First-Time Buyer Programs in South Lyon
Buyers in South Lyon have access to a mix of state, county, and federal resources designed to cut down out-of-pocket closing costs. These range from zero-interest loans to standard federal mortgages with relaxed credit requirements. The Michigan State Housing Development Authority (MSHDA) manages the primary statewide initiatives, while the Oakland County Treasurer’s Office handles local funds. Knowing which entity provides which benefit will save you a lot of confusion when you’re talking to lenders.
State-Level Options Through MSHDA
MSHDA is Michigan’s state housing finance agency. They run the MI Home Loan program, which pairs a standard mortgage with down payment assistance for eligible buyers – and yes, that includes people buying in South Lyon. You’ll need to work with an approved participating lender to access the funds; you can’t go around them.
Local Programs in Oakland County
South Lyon sits in Oakland County, which means you can also look into the county’s own Home Buyer Assistance Program. The Oakland County Treasurer’s Office runs this one in partnership with Independent Bank. One thing to know upfront: this program requires you to contribute at least $1,000 of your own personal funds toward the purchase. It’s not a free ride, but it can work well alongside the state offerings.
Federal Loan Options
FHA, VA, and USDA mortgages round out the picture. FHA loans allow down payments as low as 3.5%, which makes them a standard choice for buyers with limited cash reserves. VA loans offer zero-down financing for eligible veterans and service members. USDA loans also provide zero-down options, though you’ll need to verify that your specific target property falls within an eligible rural boundary – that’s not something you want to assume.
Down Payment Assistance and Grants Available to Buyers
The most prominent statewide option is the MI 10K DPA program, which provides up to $10,000 in assistance as a zero-interest, zero-monthly-payment loan. You don’t make monthly payments on it. Instead, the balance is repaid when you sell the home, refinance the mortgage, or pay off the loan completely. That structure keeps your monthly housing costs lower while still covering your upfront requirements.
Available Grant Amounts and Assistance Types
Technically the MI 10K DPA is a silent second mortgage, not a traditional grant – it stays attached to the property until a qualifying event triggers repayment. At the county level, the Oakland County Treasurer’s program offers its own tier of financial help. Ask your loan officer to run a side-by-side comparison of the MSHDA program against the county’s Independent Bank partnership. The right answer depends on your specific numbers.
Low and No-Down-Payment Options
For a $342,000 median-priced home in South Lyon, a 3.5% FHA down payment comes out to roughly $11,970. Apply the $10,000 MSHDA assistance to that scenario and your out-of-pocket cash requirement gets very small. If you qualify for a VA loan, you’re looking at a true zero-down purchase without needing state assistance at all.
Who Qualifies for First-Time Buyer Programs in Michigan
These programs look at household income, household size, and purchase price. The standard definition of “first-time buyer” here is straightforward: you haven’t owned a principal residence in the past three years. Both the state and the county enforce strict income caps to make sure the funds reach the people they’re meant for, and lenders will verify every source of household income during underwriting.
Income Limits and Household Size
Oakland County’s program caps eligibility at 120% of the Area Median Income – for 2026, that limit sits at $127,320 for the county. MSHDA’s statewide limits are a little more variable; they depend on household size and whether the home is in a targeted area, and they generally range from about $91,200 to $174,720 depending on your specific circumstances.
Credit Score and Debt Guidelines
You’ll need to meet the minimum credit score requirements set by both the participating lender and the housing authority. FHA loans can accommodate lower scores, but state assistance programs typically require at least a 640. Your debt-to-income ratio matters too – lenders want to see that your total monthly debts, including the new mortgage payment, don’t consume too much of your gross monthly income.
Affording a Home in South Lyon Right Now
With the median sale price at approximately $342,000, it’s worth running your numbers before you ever step into a showing. Local inventory recently sat at around 66 available homes – enough to give you some choices, but not enough to take your time.
Property taxes, homeowners insurance, and potential HOA fees all stack on top of your base mortgage payment. A simple affordability exercise makes the salary question concrete.
The 3-3-3 Rule for Home Buying
The 3-3-3 rule is a useful back-of-the-envelope check. It suggests saving 3% of the purchase price for the down payment, keeping your mortgage payment under 33% of your gross monthly income, and holding 3 months of expenses in reserve for emergencies. Applied to South Lyon, the 3% down payment on a median-priced home means having roughly $10,260 saved. The emergency cushion is there so that a busted water heater three weeks after closing doesn’t derail you.
Income Needed for a Typical South Lyon Home
Buying at $342,000 with a 3.5% down payment leaves a loan balance of about $330,000. For illustration only: at a 6.5% interest rate, principal and interest would run roughly $2,085 per month. Once you add taxes, insurance, and mortgage insurance, the total monthly payment easily approaches $2,700. To keep that under one-third of your gross income, you’re generally looking at a household salary of around $97,000 to $100,000.
Down Payment Requirements by Loan Type
The cash you need at the closing table depends entirely on which mortgage product you choose. Conventional loans for first-time buyers can go as low as 3% down. FHA loans require a strict 3.5% minimum. VA and USDA loans require 0% down, provided both the buyer and the property meet the respective guidelines.
What a $10,000 Down Payment Buys You
A $10,000 down payment covers the 3% minimum for a conventional loan on a purchase price up to about $333,000 – which lines up closely with where South Lyon’s median sits right now. On an FHA loan, that same $10,000 covers the 3.5% requirement on a home priced up to $285,000. If you’re looking at anything higher, you’ll need to supplement your savings or layer in down payment assistance.
Finding Participating Lenders and Tax Credits
State and county assistance programs require you to work with specific approved lenders. MSHDA maintains a network of these partners across Michigan, and Mortgage 1 has been noted as a top MSHDA lender statewide since 2013. For the Oakland County program, you’ll need to coordinate with Independent Bank. Your loan officer handles the assistance program paperwork alongside your primary mortgage application – it’s not a separate process you manage on your own.
One more thing worth asking your lender about: Mortgage Credit Certificates (MCC). An MCC converts a portion of your annual mortgage interest into a direct federal tax credit, which can free up additional cash at tax time. Not every lender brings this up, so ask.
How to Apply for a First-Time Buyer Loan in South Lyon
Start by pulling together your financial documents: two years of W-2s, two years of tax returns, recent pay stubs, and two months of bank statements. Then contact a participating lender who handles either MSHDA or Oakland County assistance programs. They’ll pull your credit and calculate your debt-to-income ratio.
Once the lender verifies your income and assets, they’ll issue a pre-approval letter. Take that letter to a real estate agent and you’re ready to start touring homes in the 48178 ZIP code. The sequence matters – pre-approval first, then houses.
Frequently Asked Questions
What disqualifies you as a first-time home buyer in Michigan?
You’re disqualified if you’ve owned a principal residence at any point in the past three years. You’ll also be disqualified if your household income exceeds the MSHDA or Oakland County limits, or if your credit score falls below the lender’s minimum requirement.
What is the first-time home buyer grant in South Lyon, Michigan and how much is it?
South Lyon buyers can access the statewide MI 10K DPA program, which provides up to $10,000 as a zero-interest loan repaid when you sell or refinance. Alternatively, buyers can use the Oakland County Home Buyer Assistance Program, provided they contribute at least $1,000 of their own funds.
How much down payment do first-time buyers need in Michigan?
It depends on the loan type. Conventional loans require as little as 3%, FHA loans require 3.5%, and VA or USDA loans require 0% down.
What salary do you need to afford a $300K–$400K house in South Lyon, MI?
To keep housing costs under one-third of your gross income in that price range, a household salary between $90,000 and $120,000 is generally recommended – accounting for principal, interest, property taxes, and insurance.
What are the exact steps to apply for a first-time buyer loan in South Lyon?
Gather your income documents, tax returns, and bank statements first. Then contact a MSHDA-approved lender or Independent Bank to apply for pre-approval and confirm your eligibility for local assistance programs.
Are there specific tax credits for first-time home buyers purchasing in South Lyon, MI?
Yes. Eligible buyers can apply for a Mortgage Credit Certificate (MCC) through their lender. It converts a portion of your annual mortgage interest into a direct federal tax credit.
Can I use first-time buyer grants for a newly built house in South Lyon?
State and county assistance programs can generally be applied to newly built properties, provided the purchase price falls within the required limits. If you are financing new construction properties in South Lyon, your lender will simply verify that the house meets all standard FHA, VA, or conventional loan guidelines.
Do assistance programs restrict the style of house I can buy?
Most state and county programs require the house to be your principal residence, but they cover several residential property styles in the area. Whether you choose a detached house or a condo, the property just needs to meet the appraisal guidelines for your specific loan type.